
Raising your insurance deductible can lower your premium, but the saving is only useful if you can handle the larger share of a covered loss. Start with a written quote and cash available today, not a rule of thumb about choosing the highest deductible.
Here is a practical way to decide without guessing. You will need your current policy, a written alternative quote and a look at the savings you can actually use.
This guide covers personal auto and homeowners insurance in the United States. Renters can use the same comparison method for property deductibles. Health insurance has different cost-sharing rules and is not covered here.
Check your state’s rules. Texas Department of Insurance examples below explain particular issues; they do not establish nationwide claim deadlines, fault rules or deductible-recovery rights. Check your policy and your own state insurance department for the rules that apply where you live.
Should you raise your deductible? Start with three checks
Consider a higher deductible only after you have checked three things:
Available cash: Could you cover the new deductible without missing essential bills or relying on expensive borrowing?
Actual savings: How much would an otherwise matching policy save over the same period?
The loss scenario: Would this deductible apply to the damage you are worried about, and could other deductibles or uncovered costs arrive with it?
There is no single deductible that works for every household. Keeping a lower one while you build savings is a valid choice, not a financial failure.
What an insurance deductible really means
A deductible is the part of a covered loss that you are responsible for. Your premium is the price you pay to keep the policy.
For a simple example, suppose your insurer accepts $4,000 of covered repair damage and the applicable deductible is $1,000. Assuming no other adjustments or limits, the insurer's payment would be $3,000. You would be responsible for the remaining $1,000.
You do not necessarily send that $1,000 to the insurer before anything happens. It is often subtracted from the claim payment, leaving you to cover the difference in the repair bill.
A higher deductible generally reduces the premium because you are agreeing to take on more of a covered loss yourself. The exact price difference depends on the policy and insurer. Get a quote rather than relying on a promised percentage saving. [1][2]
Also, your deductible is not a cap on everything a loss could cost you. Excluded damage, amounts above policy limits, depreciation and other policy terms can leave you paying more.
Step 1: Find the money that would actually be available
Start with this question:
If a covered loss happened tomorrow, how much could I use without leaving rent, food, utilities or other essential commitments unpaid?
That number may be smaller than your savings-account balance.
Suppose you have $2,400 saved:
Scroll sideways to see every column.
Money already needed | Amount |
|---|---|
Essential bills due before your next reliable income | $1,200 |
Other committed spending, not included above | $400 |
Savings left after those commitments | $800 |
These are hypothetical amounts, not a recommended budget.
On paper, you have $2,400. But choosing a $2,000 deductible on that basis would ignore money already needed elsewhere.
Even the remaining $800 may be serving other emergencies. You do not have to create a separate account for every risk, but do not mentally promise the same dollars to several bills at once.
A credit limit is not savings. Borrowing might help bridge a genuine emergency, but interest and fees can make the eventual cost larger. The CFPB recommends keeping emergency money safe and accessible and notes that even a small reserve can help. [3]
What the savings data actually show
In the Federal Reserve's 2025 household survey, published in May 2026, 63% of adults said they would cover a hypothetical $400 emergency entirely with cash, savings or a credit card paid off at the next statement.
That does not mean the other 37% had no money or could not pay. Some would borrow or sell something, and some might choose not to use available cash. Separately, 12% of all adults said they could not cover the expense by any means. [4]
The same survey asked the largest emergency expense adults could handle using only savings. The distribution below is more relevant to cash planning than assuming everyone who would use credit has no cash. These are national survey responses, not a recommended deductible or a forecast of insurance claims.
Source: Federal Reserve, 2025 SHED, Table 26, published May 2026. Percent of all adults; categories total 100%. Self-reported savings capacity, not insurance claims or a recommended deductible.
The practical point is simple: available cash matters. An insurance decision should fit the resources you have now, not the savings you hope to have later.
Step 2: Ask for a comparison that changes only the deductible
A cheaper quote does not tell you whether the deductible change is worthwhile if other coverage has changed too.
Ask for the same:
Insured people, vehicles or property.
Coverage limits and relevant endorsements.
Replacement-cost or actual-cash-value settlement terms.
Policy period and payment schedule.
Discounts, fees and optional coverages.
Then compare the deductible options.
The NAIC recommends requesting matching coverage and limits when shopping for insurance and getting key quote information in writing. [2][6]
Use the total price for the same period, not just the advertised monthly installment. If an auto policy runs for six months, compare both six-month totals first. Doubling the savings gives an annualized estimate, not a guarantee that the next renewal will cost the same.
Check deductible credits and waivers before changing your policy
Some auto policies offer optional “vanishing” or “disappearing” deductible programs. Ask what credit you have earned today, which coverages it applies to, whether the feature costs extra, and what happens to the credit after a claim, a deductible change or a switch of insurer. Do not count future rewards as cash available now. Progressive’s program explanation illustrates this type of feature, not a benefit every policy includes.
Also check glass coverage separately. A windshield repair may have no deductible even when replacement would have one. For example, Progressive describes no deductible for covered windshield repairs under comprehensive coverage and a separate $0 glass-replacement option in certain states. Availability and conditions depend on the policy and state; a waiver does not mean every kind of glass damage or replacement is free.
Before dropping an endorsement or switching policies, get written confirmation of your current deductible after any earned credit, the repair-versus-replacement rules, and what benefits the new quote retains. Compare the full premium including optional-feature charges.
A worked example
Suppose you receive these otherwise matching 12-month auto quotes:
Scroll sideways to see every column.
Quote | Collision deductible | Total annual premium |
|---|---|---|
A | $500 | $1,800 |
B | $1,000 | $1,680 |
C | $2,000 | $1,560 |
These are invented comparison inputs, not market averages or quotes readers can expect. All other coverages and deductibles stay the same.
Moving from A to B saves $120 a year, or $10 a month. In return, you accept up to $500 more responsibility per applicable collision loss.
Moving from A to C saves $240 a year, or $20 a month. You accept up to $1,500 more responsibility per applicable collision loss.
Neither answer is automatically right. But the trade-off is now clear enough to evaluate.
Compare the whole year, not just the renewal bill
Using the same hypothetical quotes, add the annual premium to your share of covered collision losses. Every loss below is assumed to be at least $2,000, with the deductible applied separately. This is scenario arithmetic, not expected cost or a prediction.
Scroll sideways to see every column.
Covered collisions during the year | Quote A: $500 deductible | Quote B: $1,000 deductible | Quote C: $2,000 deductible |
|---|---|---|---|
None | $1,800 | $1,680 | $1,560 |
One | $2,300 | $2,680 | $3,560 |
Two separate losses | $2,800 | $3,680 | $5,560 |
With no collision loss, C costs $240 less than A. With one sufficiently large covered collision, C costs $1,260 more than A after including that year's $240 premium saving. With two separate losses, the difference is $2,760. The annual premium is held fixed; later claim-related renewal changes, other coverages, financing costs and uninsured damage are excluded.
Use your own quotes: total premium for the period + the sum of your shares of the assumed covered losses. Do not add the full repair bill to a deductible you already counted. Review the auto coverage guide if you are unsure which coverage would apply.
Step 3: Calculate the savings recovery time
Divide the increase in deductible by the annual premium saving:
Additional deductible ÷ annual premium saving = years of savings needed to match that additional amount
Using the example:
From $500 to $1,000: $500 ÷ $120 = about 4.2 years.
From $500 to $2,000: $1,500 ÷ $240 = 6.25 years.
Source: FinanceFirst calculations using the hypothetical annual quotes above: $500 ÷ $120 and $1,500 ÷ $240. Bars start at zero. Not a claim probability, guaranteed payback period or affordability test.
This is a simple comparison tool, not a prediction of when you will have a claim.
It assumes the saving stays unchanged and ignores interest, future premium changes and the timing of payments. It also compares the full deductible difference, which matters only when the covered damage is large enough.
Most importantly, it does not estimate your personal claim probability. A short recovery time does not make a deductible affordable, and a long recovery time does not prove it is wrong for someone with substantial savings.
If the higher deductible does not reduce the premium, there is no premium-saving case for taking it in an otherwise identical comparison.
Step 4: Test an actual loss, including a smaller one
The extra cost of a higher deductible is not always the full difference between the two deductibles.
Here is how Quotes A and C would work at three covered-damage amounts:
Scroll sideways to see every column.
Accepted covered damage | Your share with a $500 deductible | Your share with a $2,000 deductible | Additional share under the higher deductible |
|---|---|---|---|
$800 | $500 | $800 | $300 |
$1,500 | $500 | $1,500 | $1,000 |
$5,000 | $500 | $2,000 | $1,500 |
These simplified examples assume the stated deductible applies, all damage is covered, and there are no other adjustments or limits.
Source: FinanceFirst illustrative arithmetic, min(loss, $2,000) minus min(loss, $500). Same covered loss under both options; excludes limits, depreciation and other adjustments.
Check the arithmetic: your simplified share is the smaller of the accepted covered loss and the deductible. The extra share is that result under the higher deductible minus the result under the lower one. This calculation is not a complete claim settlement.
For covered damage below the deductible, you generally bear the covered repair cost rather than automatically paying the full deductible. Actual bills may include additional uncovered costs.
This is why “I save $240 and risk $1,500” is useful shorthand, but not the full decision. The amount and type of loss matter.
There is also a timing problem: if you choose Quote C today and have a large covered collision next week, you have not had six years to save the premium difference.
Future savings cannot pay today's repair bill.
Step 5: Check whether your home deductible is a percentage
A home policy may have a flat-dollar deductible for some losses and a different deductible for wind, hail, hurricanes or other events.
If one is expressed as a percentage, convert it into dollars before comparing quotes.
For illustration, if the policy calculates a 2% deductible using a $350,000 dwelling coverage limit:
$350,000 × 2% = $7,000
That is not 2% of a $10,000 repair bill.
If the relevant limit rose to $400,000 at renewal and the same 2% rule applied, the deductible would become $8,000.
These are arithmetic examples, not a description of every policy. Ask which coverage amount the percentage uses, what event triggers it, and whether any minimum, maximum or special rule applies.
The Texas Department of Insurance specifically warns consumers to translate percentage deductibles into dollars. NAIC guidance also notes that catastrophe deductibles may be expressed as percentages. [1][2]
The homeowners coverage and rebuilding-cost guide explains why the insured limit also needs its own review. Do not reduce that limit just to reduce a percentage deductible.
Write each applicable deductible down separately. A low “all other perils” deductible does not tell you what you would owe after a hailstorm.
Step 6: Stress-test one event across multiple policies
Home and auto property deductibles commonly apply per claim or loss, rather than working like one annual health-insurance deductible. Some catastrophe provisions and state rules work differently, so check your own terms. [1][2]
Two separate covered collisions in one policy year could therefore mean paying a deductible twice.
One weather event can also affect more than one policy.
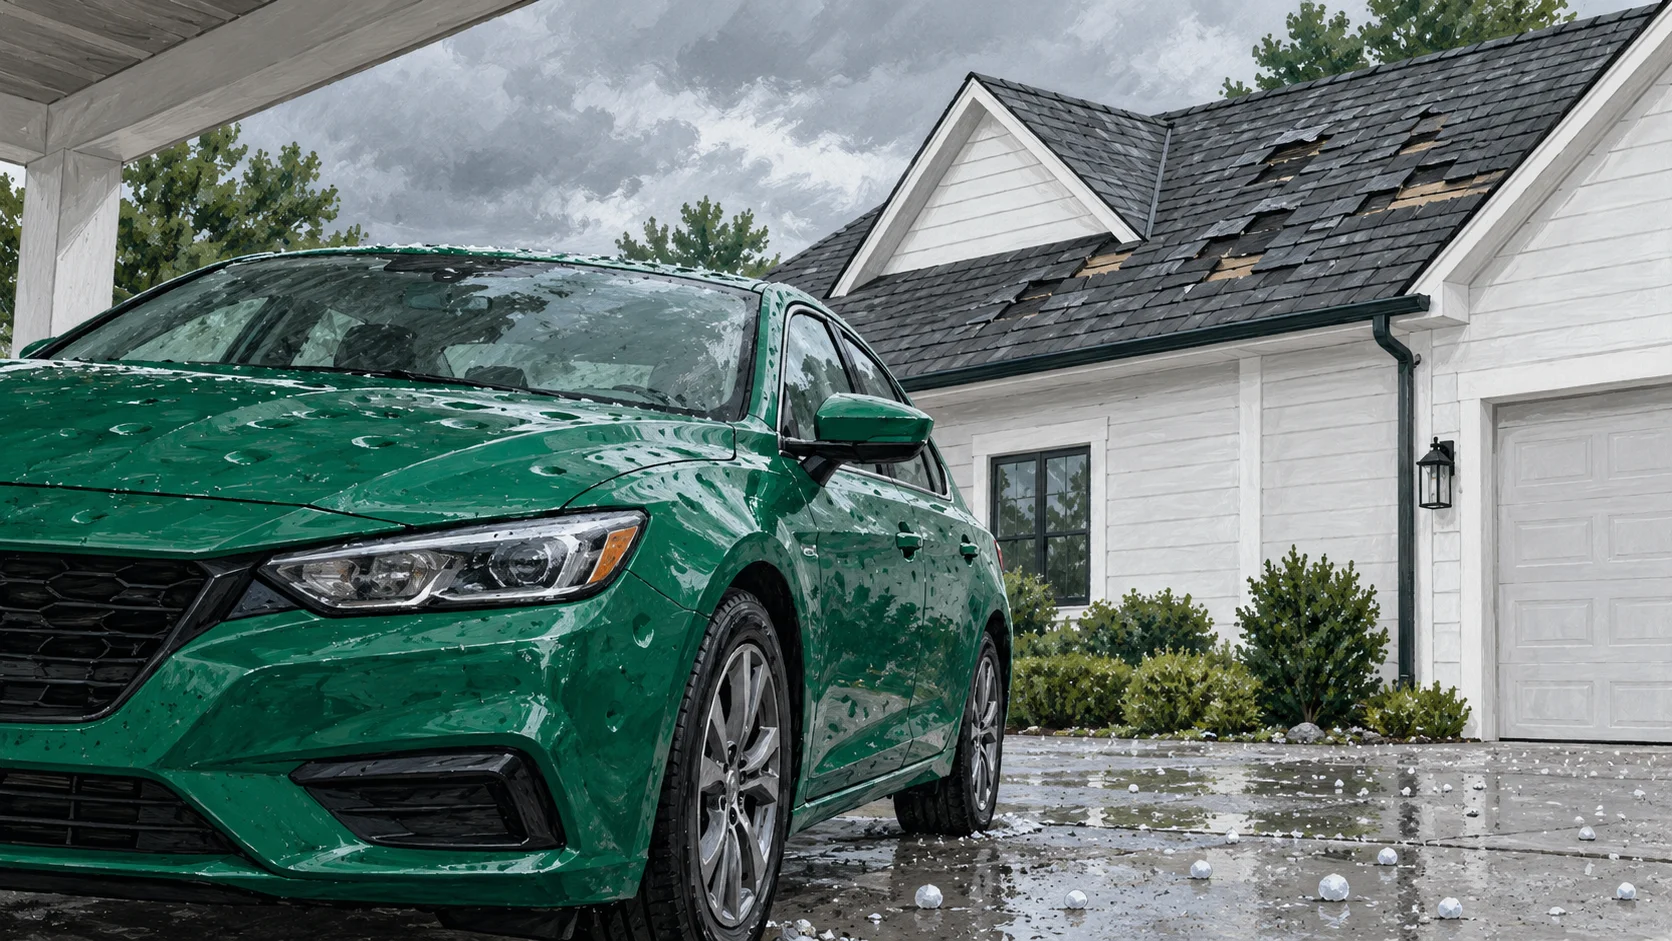
For example, assume a hailstorm causes covered damage to a roof and a car. The applicable home deductible is $3,000, and the car's comprehensive deductible is $1,000. If both covered losses exceed their deductibles, the household could be responsible for $4,000 across the two claims, before other costs.
That is a hypothetical stress test, not a claim that every storm produces two deductibles. Bundling the policies does not automatically create one shared deductible. Ask whether a specific single-loss provision changes the result.
You do not need to assume every possible emergency happens together. Start with a realistic event for your location and household.
Ask yourself: Does my cash plan still work if this happens before I have rebuilt my savings?
A lower deductible does not repair a coverage gap
Before paying more for a lower deductible, make sure the policy covers the loss you care about.
For auto insurance, collision and comprehensive are different coverages. Comprehensive generally addresses non-collision events such as theft, hail, fire and flood, subject to the policy. Changing the collision deductible does not necessarily change the comprehensive deductible. [6]
For homeowners insurance, ordinary flood damage is generally excluded from standard policies. Lowering a homeowners deductible does not add flood coverage. [2]
Also check how the insurer values damaged property.
Actual-cash-value coverage generally subtracts depreciation. Replacement-cost coverage works differently, but payment may still be staged and subject to repair or replacement requirements. The Texas regulator explains that an initial payment under replacement-cost coverage may deduct both depreciation and the deductible, with further payment available after qualifying work is completed. [7]
See our replacement cost versus actual cash value explanation for the settlement distinction.
That creates two separate questions:
How much will I ultimately be responsible for?
How much cash might I need before the final reimbursement arrives?
A good quote comparison asks both.
What to do if the higher deductible is not affordable
You still have options. Keeping the current deductible does not mean you have stopped looking for savings.
Compare other insurers on matching coverage
Different insurers can price the same risk differently. Compare coverage, exclusions, deductibles and service as well as the premium. Check insurer licensing and consumer information through your state insurance department. [2][6]
Do not cancel existing coverage before confirming the replacement is active and meets any lender requirements.
Ask for a rating-information review
Check that household drivers, vehicle use, mileage and property details are accurate. Ask about discounts for which you genuinely qualify, and whether a different payment schedule changes fees.
Do not understate mileage, omit a driver or misdescribe the property to obtain a cheaper quote.
Price the options separately
For auto coverage, ask what happens if you change only collision or only comprehensive. For home coverage, ask which deductible options are available for each relevant peril.
A lender or lease may restrict your choices. Check the agreement before changing coverage or deductibles.
Build the reserve before making the change
Suppose you want an additional $600 available before reconsidering a higher deductible. Saving $50 a month reaches that amount in 12 months, assuming no withdrawals or interest.
Those are chosen planning inputs. Use an amount that fits your actual cash flow.
The CFPB emphasizes that emergency-fund needs depend on your circumstances and that small contributions still count. Automatic transfers can help, but should not create overdrafts. [3]
If neither available deductible nor premium feels manageable, ask a licensed agent or your state insurance department what alternatives exist. Do not let the search for a perfect policy cause an accidental lapse.
Copy this message to your insurer
I'm reviewing my deductible, but I want to compare the trade-off clearly.
Please send written quotes for the available deductible options with the same coverage limits, settlement terms, endorsements and payment schedule.
For each option, please confirm:
The total premium and fees for the same policy period.
Which deductible applies to which kind of loss.
The dollar amount and calculation basis of any percentage deductible.
Whether deductibles apply per loss, per event or on another basis.
Whether one event affecting my home and vehicle could trigger separate deductibles.
Any deductible restrictions required by my lender or lease.
Whether depreciation or reimbursement conditions could leave me needing cash beyond the deductible.
Please point me to the relevant policy wording so I can keep it with the quotes.
Download your deductible decision worksheet
On the live page, select Download CSV in the toolbar immediately above this worksheet. Clear the table search first to include all questions, then open the downloaded file in your spreadsheet app and fill the answer column. If you are reading a text-only or printed copy without the download control, copy the questions and record your answers separately. Keep policy numbers and personal information in your own records; the worksheet does not need them.
Insurance deductible decision worksheet
Scroll sideways to see every column.
Question | Your answer |
|---|---|
What coverage and type of loss am I comparing? | __________ |
What period do both quotes cover? | __________ |
What is the current deductible after earned credits, and do any waivers apply? | __________ |
What is the proposed deductible in dollars? | __________ |
How much more could I owe for a sufficiently large covered loss? | __________ |
What is the premium saving over the same policy period? | __________ |
What is the annualized saving, if relevant? | __________ |
What covered-loss amount am I stress-testing? | __________ |
What is my share of that loss under each option? | __________ |
How long would unchanged savings take to match the extra deductible? | __________ |
How much accessible cash remains after essential commitments? | __________ |
What other costs or deductibles could arrive with this loss? | __________ |
Does the choice satisfy my lender or lease? | __________ |
What temporary cash is needed before any later reimbursement? | __________ |
When do the quote and any proposed change take effect? | __________ |
Treat a blank as “not yet checked,” not zero.
If the saving is worthwhile, the terms are clear and the loss would be manageable with today's resources, a higher deductible may fit.
If the saving is small or the choice would leave you borrowing for basic repairs, keeping the lower deductible may be more useful.
If the policy does not cover the risk you are worried about, resolve that before focusing on the deductible.
Common questions
Is a $500 or $1,000 auto deductible better?
Neither is universally better. Compare written quotes with matching coverage, then ask whether you could cover the higher amount without disrupting essential bills. Also check whether the deductible applies to collision, comprehensive or another coverage.
Do I have to pay the deductible if the damage costs less?
In a simple property-damage claim, the insurer generally pays nothing when accepted covered damage is below the applicable deductible. You do not automatically owe the entire deductible; your repair bill is separate. Coverage, repairs and other claim adjustments still matter.
Will I pay a deductible if another driver causes the accident?
It depends on the claim route, coverage and state rules. Your own collision coverage may apply its deductible even if another driver caused the crash. Recovery from the responsible party may allow some or all of it to be returned, but that is not guaranteed. Ask the insurer about the process. The Texas regulator describes this potential recovery in its auto-insurance FAQ; rules elsewhere can differ. [5]
Should I avoid filing every claim near the deductible?
Do not use a blanket rule. A small property payment may not be worth pursuing in some circumstances, but reporting obligations, injuries, liability, hidden damage and deadlines can change the decision. Follow your policy's notice requirements. NAIC guidance notes that claim history can affect premiums and renewal, but does not establish a universal dollar threshold for filing. [2][6]
Should I keep a separate deductible fund?
It can make planning easier, but it is not mandatory. What matters is that the money is accessible and not already committed elsewhere. A deductible reserve is part of emergency planning, not a replacement for planning for job loss or uninsured expenses.
Before you accept the new quote
A lower premium is useful when the trade-off works for you.
Before raising a deductible, get the price difference in writing, turn any percentage into dollars and test what a realistic claim would do to your available cash.
You do not need to predict the next accident or storm. You need a policy whose responsibilities you understand and a plan you could use if something happens.
Keep both written quotes and the relevant policy terms. Confirm the effective date before changing anything. Add a deductible check to your annual insurance review, especially when dwelling limits or available savings change.
Sources and calculation notes
Evidence reviewed November 1, 2026. This article combines U.S. regulator and public-agency guidance with FinanceFirst's illustrative arithmetic. Linked insurer pages illustrate optional deductible features and glass rules; they are not endorsements or evidence that every policy offers the same benefits. No new survey, insurer quote collection or claim-probability study was conducted. Policy language and state law control actual coverage.
[1] Texas Department of Insurance, “What to know about deductibles.” Explains flat and percentage deductibles, per-claim application and the affordability trade-off. The article does not adopt its illustrative maximum premium-saving percentage as a general forecast. https://www.tdi.texas.gov/tips/deductibles.html
[2] National Association of Insurance Commissioners, “A Consumer's Guide to Home Insurance,” sections on deductibles, coverage, quote comparison and claims. Higher deductibles can lower premiums, but consumers need to be able to afford their share of a loss. https://content.naic.org/sites/default/files/publication-hoi-pp-consumer-homeowners.pdf
[3] Consumer Financial Protection Bureau, “An essential guide to building an emergency fund.” Supports accessible reserves, situation-specific goals, small contributions and the caution about borrowing and overdrafts. https://www.consumerfinance.gov/an-essential-guide-to-building-an-emergency-fund/
[4] Board of Governors of the Federal Reserve System, “Economic Well-Being of U.S. Households in 2025,” Savings and Investments, published May 2026. The 63% figure describes how respondents would pay a hypothetical $400 expense, including a credit card paid off at the next statement. Table 25 separately reports 12% unable to cover it. These are adult survey responses, not insurance-claim statistics. https://www.federalreserve.gov/publications/2026-economic-well-being-of-us-households-in-2025-savings-investments.htm
[5] Texas Department of Insurance, “FAQ: Auto insurance, claims, coverage issues, and more.” Explains using one's own collision coverage in a disputed-fault claim and the possibility of deductible recovery. This is Texas consumer guidance, not a nationwide guarantee of reimbursement. https://tdi.texas.gov/consumer/auto-insurance-faq.html
[6] National Association of Insurance Commissioners, “Consumer's Guide to Auto Insurance.” Supports coverage distinctions, lender requirements, quote comparison, claim handling and possible effects of claims. Consult the actual policy and state rules for fault-related deductible recovery. https://content.naic.org/sites/default/files/publication-aut-pp-consumer-auto.pdf
[7] Texas Department of Insurance, “Home insurance guide.” Supports settlement-method distinctions, potential staged replacement-cost payments, declarations-page information and claim-notice cautions. Texas-specific procedural rules should not be read as nationwide rules; this article does not apply its state deadlines elsewhere. https://www.tdi.texas.gov/pubs/consumer/cb025.html
Calculation notes: All premiums, individual balances, loss amounts, deductible options and savings targets in worked examples are hypothetical, except the explicitly attributed Federal Reserve findings. Savings recovery time equals additional deductible divided by annual premium saving and assumes unchanged savings. Simplified own-share calculations use the smaller of accepted covered damage and the deductible, excluding other costs and policy adjustments. Percentage examples assume the stated dwelling coverage limit is the contractual calculation basis. The examples are decision aids, not forecasts, insurer offers or guarantees.
Disclaimer: This article provides general education, not individualized insurance, legal or financial advice. Coverage, deductibles, eligibility and claims practices vary by insurer, policy and state. Read the full policy and consult a licensed insurance professional or your state insurance department about your circumstances.